Can I Get a Business Loan Without Collateral?
Short answer: yes. I fund unsecured deals every week. But "no collateral" doesn't mean "no strings attached" — and if you talk to five people in this industry, you'll get five different answers about what that actually means. Here's the real one, from someone who's been doing this for five years and closes 30-35% of the deals that come across my desk.

What "No Collateral" Actually Means
No collateral means there's no hard asset securing the loan — no lien on your building, no lender coming after your equipment if things go sideways. That's real, and it's the whole appeal.
What it doesn't mean is "no responsibility." Every revenue-based term loan and merchant cash advance I've ever structured comes with a personal guarantee. And most funders won't file a UCC lien unless you miss a payment or the funding size crosses a certain threshold — that part varies by platform.
So the honest version is: no asset at risk, but you're still on the hook personally if the business can't pay it back. Anyone who tells you otherwise is selling you something.
What Banks Actually Want As Collateral
When a bank says "secured," here's the list they're working from: a second home, an investment property, an owner-occupied building, real estate in general, a 401(k), a money market account, stocks — basically anything they can liquidate if the loan goes bad.
Here's the problem. The majority of business owners I talk to have none of that. Not the investment property, not the 401(k) sitting there unused, nothing — except their personal residence. And banks won't touch a personal residence for a business loan. So for most of the people who call me, "just get a secured loan" was never actually on the table to begin with.
A Real Example: Choosing Unsecured On Purpose
Not every story here is about someone who had no assets. One client had a bank offer him a secured business line of credit — but the collateral was his money market account. He didn't love the idea of tying up that account to fund the business, so he opted for an unsecured line instead, even though it cost more. He made an informed trade: liquidity and peace of mind over a lower rate.
A Real Example: No Assets, Real Timeline
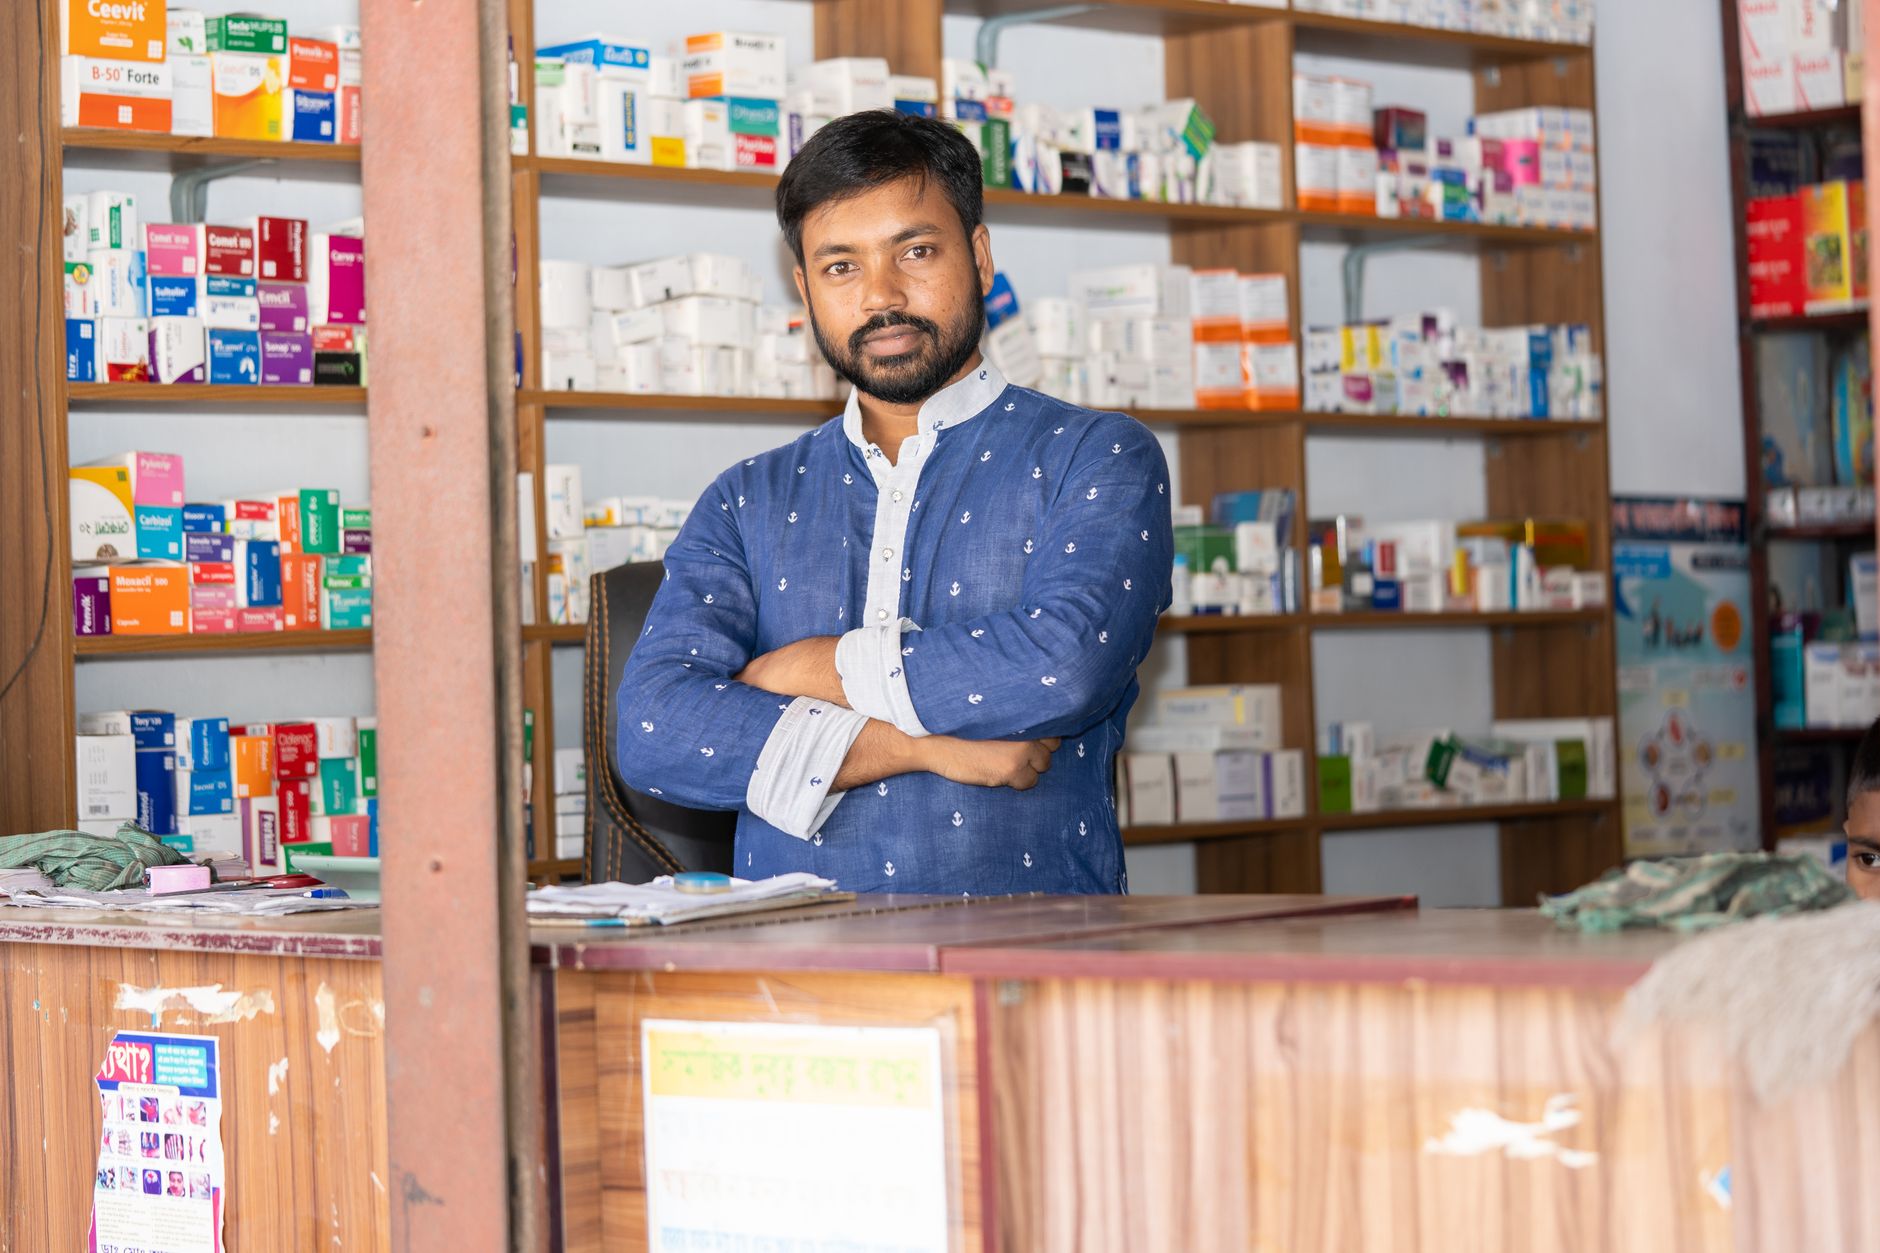
I worked with a pharmacy owner building out a brand-new location. He needed $150,000 — about $20K for the down payment on the lease, $130K for renovations. He didn't own the land or the building; he was leasing. No real estate meant no collateral, which meant the bank's five-to-ten-year term loan wasn't happening for him.
I structured $150,000 over 18 months with a weekly payment his cash flow could actually support. He's local, we still stay in touch, and he hasn't needed funding since — but he knows exactly where to find me if that changes.
What Determines Approval (When There's Nothing To Put Up)
If you've got no assets, here's what actually drives your approval and your terms. Revenue: I look at 4 months of business bank statements and run a cash flow analysis. Credit: 700+ with no asset still usually means a daily or weekly payment; every so often someone qualifies for one of my monthly-payment lines of credit — I call those people unicorns. Existing positions: if you already have one or two advances out, adding a third or fourth is a specialty of mine, but it changes the math. Strategy: are you planning to carry the balance like a term loan, or draw and repay as needed?
As a rule of thumb, I can typically match 100-125% of your average monthly gross deposits, depending on what else is already in place.
The Trade-Off You Need To Go In Knowing
Unsecured capital costs more and moves faster. Terms are shorter, and if you're in a later position (third or fourth), the cost goes up because the risk is higher. If it's a first position, we can build in early-payoff incentives and there's no prepayment penalty — it's about structuring something that matches how fast you actually want to be done paying it back.
The single biggest misconception I run into: that this space is predatory, one hundred percent loan-shark territory. If that's someone's gut reaction, I'm probably not the right fit for them — and honestly, that reaction usually comes from someone who didn't have a plan for the money the first time around. This isn't meant to keep the lights on. It's too expensive for that. It's meant to fund growth — expansion, buildout, opportunity — where there's a clear plan for the cash flow the money will produce.
Who This Is Actually Best For
High-transaction, high-deposit businesses: dental offices, medical practices, med spas — anyone processing payments multiple times a week. If you're only making one or two deposits a month, you're a harder risk and your cash flow is tighter by definition. The businesses ringing the register two or three times a week are the ones where unsecured funding genuinely shines.
What I Do Differently
Most of my competition charges a broker fee on top of what the funder charges, plus a markup on the rate. I don't charge a broker fee. I don't charge a consultation fee. I get paid when the money actually lands in your account.
I also don't stack a new position on top of an advance you took out in the last 30 days — that's a red flag to every funder in the industry, and it usually means someone's about to take on more than they can handle. If there's a real need and a real plan, I structure it as a short-term bridge — designed to be in and out before your existing position is even up for renewal.
And I stick around. I check in weekly, sometimes more. I know my clients' kids' names. Once your info hits the alternative funding space, you'll get a hundred calls from people trying to sell you money — I can't control that. What I can control is making sure my number is the one already saved in your phone.
By the numbers: average approval is $75,000, average time to fund is 24-48 hours (faster or slower depending on how quickly you move), and about 8 out of 10 clients come back to me again — not because something went wrong, but because it went right.
Secured vs. Unsecured: Questions to Ask Yourself First
Do I actually own an asset I'd be willing to risk — real estate, a 401(k), an investment account? If not, am I comfortable with a personal guarantee instead of a lien? Is this money for growth and opportunity, or to keep a struggling business afloat? How fast do I realistically want to pay this back — months, or years? Do I already have an advance or loan in place, and if so, how recent? Is my business processing frequent, steady deposits, or a few large ones a month?
If you're weighing secured against unsecured and want a second set of eyes on your specific numbers, send over 4 months of bank statements and I'll walk you through what you actually qualify for — no broker fee, no consultation fee, just a straight answer.