Merchant Cash Advance vs. Business Loan: Which Is Right for You?

Merchant Cash Advance vs. Business Loan: Which Is Right for You?

An honest, experience-based breakdown from someone who's funded both sides of this decision for six years — real case studies, real numbers, real trade-offs.

Small business owner reviewing finances to decide between merchant cash advance and business loan
Photo by PNW Production on Pexels

If you've been Googling this question, you've probably landed on a dozen articles written by content teams who have never sat across from a business owner deciding how to fund their next move. I have. For the last six years, I've helped business owners across Jacksonville, Ponte Vedra, St. Augustine, and St. Johns access capital fast through my Capital Partner Program — and I've watched what happens when they get this decision right, and what happens when they get it wrong.

Here's something to clear up first: what most people call "Revenue Based Funding" today is a rebranded version of the merchant cash advance. Same product, new name. I'll use both terms in this post because you'll see both out there, but don't let the rebrand confuse you into thinking it's something fundamentally different.

Here's the honest breakdown of merchant cash advance vs. business loan — not the sanitized version, the real one.

Why Business Owners Default to "I Want a Business Loan"

Almost every business owner starts here: they want the lower rate and the longer term, because that means a lower monthly payment. Makes sense on paper.

What most of them don't realize until we dig in is what it actually takes to get that loan. Banks and SBA lenders typically want: a 700+ credit score, two to three years of business tax returns, and those tax returns showing positive net profit for each of those years.

That last one trips up more people than anything else. If you're a smart business owner, you're not showing Uncle Sam a big profit — you're minimizing what you report. Banks want to see profit. MCA lenders care about your cash flow, not your tax strategy. That single mismatch disqualifies a huge number of otherwise strong businesses from ever getting a bank's rate in the first place.

A Real Case: When Qualifying for the Bank Wasn't the Point
Restaurant franchise storefront representing a multi-location small business
Photo by Joe Chen on Pexels

I worked with a client who owned 18 Subway locations along a main highway in Connecticut, split 50/50 with a business partner. Stellar time in business. Credit scores north of 700. Tax returns that would make any underwriter smile.

He didn't go the bank route — and it wasn't because he couldn't. It's because he understood what a bank loan actually costs beyond the rate. Once you take a bank loan, the relationship doesn't end at funding. The bank wants updated P&Ls, balance sheets, month-to-date and year-to-date transactions on an ongoing basis. The bank doesn't just become your lender — it becomes a partner in your business.

He and his partner didn't want that. They wanted speed, low documentation, and a payment that wouldn't strangle their cash flow. They were willing to pay a premium for autonomy. That's the trade-off in one sentence: a bank loan buys you a lower rate and a partner. An MCA buys you speed and your independence.

Not sure which trade-off makes sense for your business? Book a free call and we'll walk through your numbers together.

Book Your Free Call

The Real Cost Comparison Nobody Explains Right

Here's how I actually break this down for clients, because the "rate" conversation is misleading on its own.

With a bank loan, yes — you get a lower rate and a lower payment. But you're paying that cost over five years instead of one. The total interest you pay for the capital doesn't disappear just because the payment feels smaller — it's just stretched out. With an MCA, you pay a premium, but you're in and out in months, not years.

The real question isn't "what's the rate?" It's: how long do you want to be tied to debt? An MCA is a sprint. A bank loan is a five-year commitment — and nobody can promise you what your business, or the economy, looks like five years from now.

Where MCA Goes Wrong

Construction site workers representing cash flow challenges in the construction industry
Photo by wal_ 172619 on Pexels

I won't pretend this product is right for everyone. I've seen it go sideways in a couple of predictable ways.

Low-revenue, low-average-daily-balance businesses: Some businesses are barely making it and still technically qualify with a high-risk lender. That's a setup for trouble — thin margins mean one missed or delayed deposit throws off the whole payment schedule.

Construction: This is the industry I'd flag hardest. Construction businesses often don't forecast their accounts receivable accurately — they don't know precisely when a receivable is actually going to land. Even with a reconciliation clause built in, they can end up upside down. For construction, a business line of credit is usually the better tool. The catch: lines of credit in the alternative funding space typically require a 660+ credit score, which knocks out a lot of construction operators who'd benefit from one the most.

My advice if you're in construction and considering an MCA anyway: don't bite off more than you can chew. Take a smaller amount, a shorter term, a lower payment. A bigger advance with a longer term just means you're on the hook longer with less room to breathe if an AR gets delayed.

The Mistake That Has Nothing to Do With Rate
Restaurant renovation and dining room remodel
Photo by Magda Ehlers on Pexels

The number one mistake I see isn't people chasing the lowest rate — it's underestimating their own return on investment timeline.

Say a restaurant owner uses an MCA to remodel, add fifty tables, and expand their outdoor footprint. They expect foot traffic to jump. What they don't factor in: marketing costs, word-of-mouth takes time to build, menu awareness takes time to spread. If revenue doesn't increase as fast as expected — or just holds flat — they're still on the hook for that weekly payment.

This is where understanding your cash flow seasonality matters enormously, especially in an industry like restaurants, which is inherently cyclical. If I know a client's business has a slow season coming, I'm not going to put them on a 12-month term. I'll shorten it to 6-8 months so they're clear before the trouble season hits — or better yet, positioned to refinance and get more capital to get through it. It's strategy, not just funding.

Who's a Strong Fit for MCA — and Who Isn't
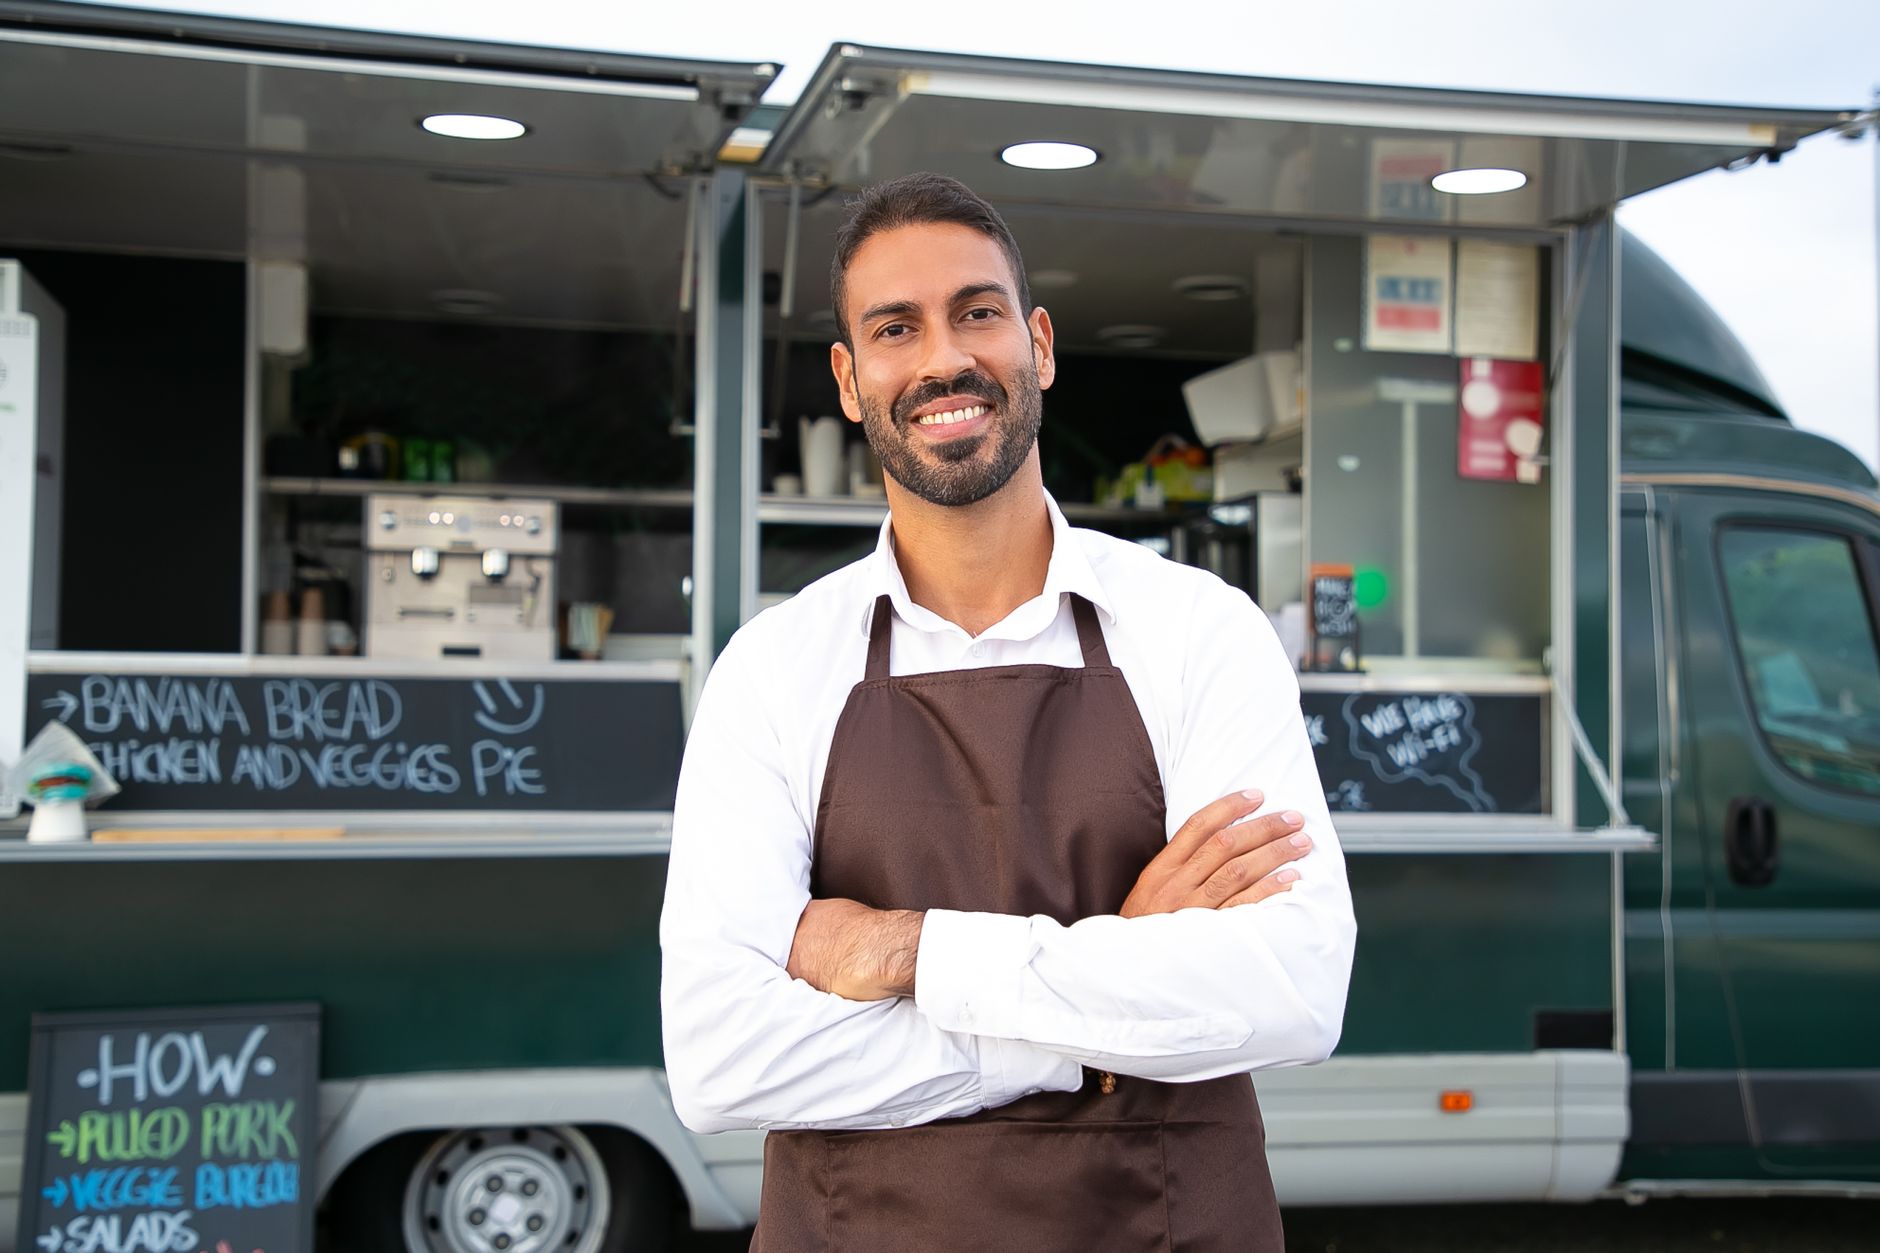
Food truck business owner representing high-transaction businesses well suited for merchant cash advance
Photo by Kampus Production on Pexels

The best candidates for MCA are high-transaction, high-deposit businesses — generally ten or more deposits a month. Think restaurants, spas, doctors' offices: steady, recurring cash flow and decent time in business.

Businesses with five or fewer deposits a month are riskier, because MCA payments come out daily or weekly. If your deposits are infrequent, one delay can throw your whole cash flow out of balance. I do fund single-truck owner-operators, and I'll be straight with you: it's high risk. One truck, minimal deposits, already-tight margins, high diesel costs. I much prefer operators running five or more trucks — if one truck goes down, the business doesn't stop.
Think your business is a strong fit for fast, flexible funding? Let's find out together.

Get Funded Now

The Trap to Avoid: Stacking

If you need $250,000 and only qualify for $150,000, do not take a second advance on top of the first to make up the difference. That's called stacking, and it's a red flag across the entire industry. Funders who see multiple positions taken within 30 days get cautious fast, and for good reason — it usually means someone needed more money than they should have taken on.

If you do end up over-extended with multiple advances, my advice is blunt: don't go to a settlement company. I've watched too many business owners end up worse off after going that route. Don't stop payments, don't default, don't hire an attorney reflexively. Talk directly to your funders and work out a plan to honor your obligations. It costs far less than the alternative.

Already stacked or feeling stretched thin? Get on a call with me before you make it worse — I'd rather help you unwind it than watch you go to a settlement company.

Talk to Me Now

Used Right, It's a Weapon — Not a Trap

Here's my actual belief on this, and I don't say it to be a salesman: an MCA, with the right broker and the right lending partnerships, is one of the most powerful tools available for growing and scaling a business — if you understand your own cash flow and use it responsibly.

I'm not interested in convincing skeptics that leveraging capital is smart. If you think this product is predatory, I'm not the guy trying to change your mind — and you're probably not my client. But I'd rather you hear this from someone who's actually done it than get shopped around by a junior broker who doesn't know the difference between a good fit and a bad one. I've got the Google reviews and the texts from merchants who learned that the hard way and came back.

Why This Matters to Me

I got into this industry six years ago and fell in love with it. I built this business from home, and early on I struggled with cash flow myself — I didn't know there was an alternative to the bank. Once I learned how to help business owners access capital quickly, get rewarded for doing it right, and build a real relationship in the process through my Capital Partner Program, everything changed.

About 80% of my merchants come back. I check in, I send a message, I send a Christmas card — but honestly, most of the time they just know when they're ready, because we've already had the conversation about their next move. Some clients are one-and-done: they needed a bridge, I was the bridge, and I never hear from them again. That's fine too. But I'm building relationships with business owners who want a trusted partner to help them navigate this space — not just a transaction.

The Bottom Line

If you value a lower rate and a longer runway, and you can qualify — credit score, tax returns, time in business — a traditional loan might be right for you. Just know what you're signing up for: an ongoing relationship with your bank, and years tied to that note.

If you value speed, low documentation, and getting in and out without a five-year commitment — and you understand your own cash flow well enough to use it responsibly — an MCA can be the smarter, more strategic move.

There's no universal right answer. There's only the right answer for your business, your industry, and your appetite for risk. That's the conversation I have with every business owner who calls me.

Get Funded Now Book Your Free Call With Joe

Share This Post

Subscribe To Our Newsletter

Get updates and learn from the best

More To Explore

Do You Want To Boost Your Business?

drop us a line and keep in touch